
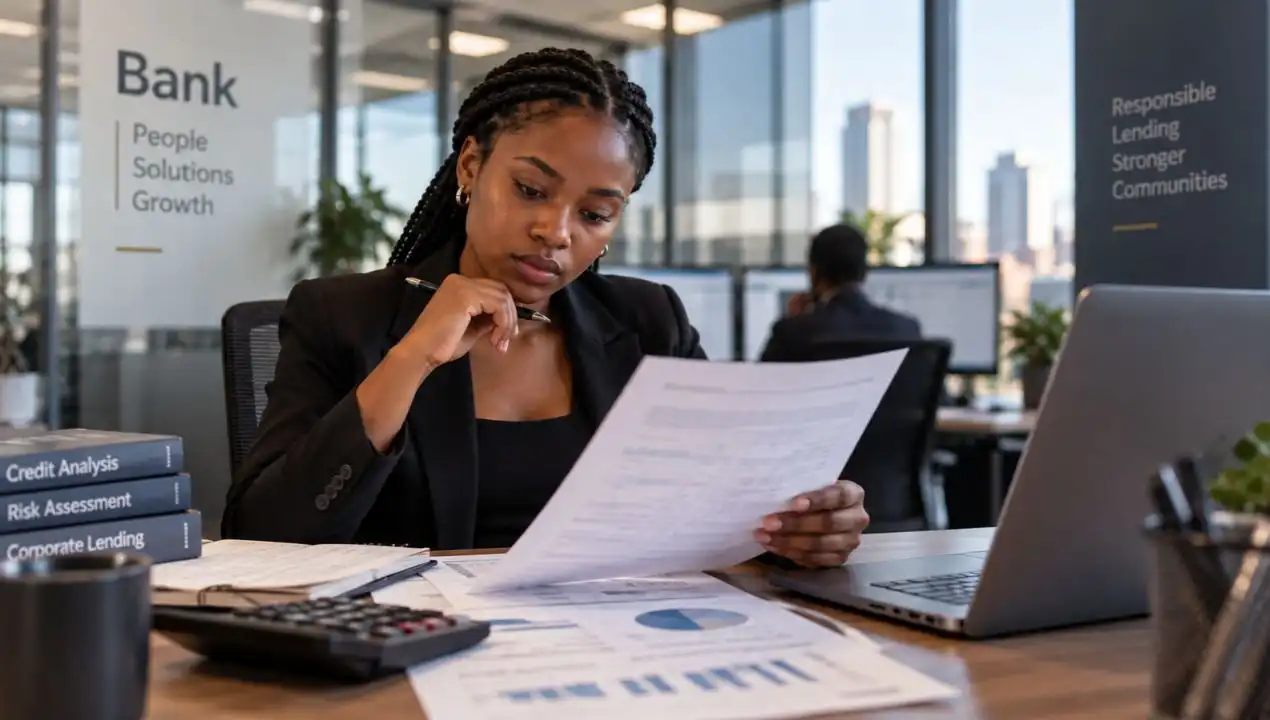
A bank credit analyst evaluates whether an individual, business or organisation is likely to repay money it wants to borrow.
The analyst studies financial information, existing debt, cash flow, repayment history, collateral and other risks before recommending whether the bank should approve the credit, decline it, change the amount or attach particular conditions.
Credit analysis therefore sits at the centre of one of banking’s most important decisions: who receives credit, how much they can borrow and how much risk the bank is taking by lending to them.
South African banks operate under detailed credit-risk requirements. The South African Reserve Bank’s Prudential Authority requires banks to measure, monitor and manage credit exposures as part of the country’s banking regulatory framework, including through its current credit-risk requirements for banks.
What does a credit analyst actually do?
A credit analyst takes information about a potential borrower and turns it into a credit recommendation.
Depending on the bank and type of lending, the work can include:
- Reviewing financial statements
- Analysing income and expenses
- Studying cash flow
- Checking existing debt
- Assessing repayment capacity
- Reviewing credit-bureau information
- Examining collateral or security
- Calculating financial ratios
- Identifying risks
- Preparing credit reports
- Recommending lending limits
- Monitoring existing borrowers
The analyst is not simply deciding whether someone is “good” or “bad” for credit.
The real question is whether the proposed lending makes sense at the requested amount, price, term and level of risk.
What is credit risk?
Credit risk is the possibility that a borrower will not repay money according to the agreed terms.
For a bank, that could mean losing some or all of the money lent.
Credit risk can arise from:
- Personal loans
- Credit cards
- Home loans
- Vehicle finance
- Business loans
- Commercial property finance
- Corporate lending
- Overdrafts
- Trade-finance facilities
The South African Reserve Bank describes credit exposure as the amount a bank is financially exposed to before taking risk mitigation into account in its banking-sector credit-risk data definitions.
Credit analysts help banks understand that exposure before and after credit is granted.
Are all bank credit analysts doing the same work?
No. Credit analysis changes significantly depending on the customer and lending product.
A bank can have analysts specialising in:
- Retail credit
- SME lending
- Commercial banking
- Corporate credit
- Property finance
- Vehicle finance
- Home loans
- Agricultural finance
- Leveraged finance
- Credit risk analytics
Analysing a R30,000 personal loan is very different from assessing a R300 million corporate facility.
The core principle is the same, but the depth of analysis changes.
What does a retail credit analyst do?
Retail credit focuses primarily on individual consumers.
The analyst or automated credit system may assess information such as:
- Income
- Employment
- Monthly expenses
- Existing debt
- Credit history
- Payment behaviour
- Affordability
Retail banking involves very large numbers of applications, so much of the initial decision-making is automated.
Analysts in these teams often work on credit policies, scorecards, portfolio performance and exceptions rather than manually reading every application.
This creates a strong overlap between traditional credit analysis and data analytics.
What does a business credit analyst do?
A business credit analyst examines whether a company can afford to repay borrowing.
The analysis usually goes deeper because business cash flows can be more complicated than a salary.
You may need to examine:
- Revenue
- Gross profit
- Operating expenses
- Profitability
- Cash flow
- Existing loans
- Assets
- Liabilities
- Working capital
- Customers and suppliers
- Industry conditions
- Management quality
You might also analyse several years of financial statements to understand whether the business is improving or weakening.
What does a corporate credit analyst do?
Corporate credit analysts generally work with larger and more complex borrowers.
These could include:
- Listed companies
- Large private businesses
- Multinational groups
- Property companies
- Infrastructure businesses
- Mining companies
The analyst may assess large lending facilities involving several banks and complex legal structures.
The work can include:
- Detailed financial modelling
- Forecasting
- Industry analysis
- Stress testing
- Covenant analysis
- Security assessment
- Group-structure analysis
- Management discussions
- Credit committee presentations
The potential losses are much larger, so the credit process can be significantly more detailed.
How do credit analysts use financial statements?
Financial statements help an analyst understand how a business earns money and whether it can support additional debt.
You may review the:
- Income statement
- Balance sheet
- Cash-flow statement
- Notes to the financial statements
The analyst is looking for more than profit.
A company can report accounting profit while struggling to generate enough cash to repay debt.
That is why cash-flow analysis is central to business credit.
Which financial ratios do credit analysts use?
The ratios depend on the borrower and industry, but common examples include:
Debt-to-equity
This compares debt with shareholder funding.
A highly leveraged business may have less room to absorb another loan.
Interest coverage
This considers whether earnings are sufficient to cover interest payments.
Debt service coverage
This measures the ability of cash flow to cover scheduled debt repayments.
Current ratio
This can help assess short-term liquidity.
Profit margins
Margins can show how efficiently the company turns revenue into profit.
Working-capital measures
These help the analyst understand how quickly cash moves through customers, suppliers and inventory.
Ratios should not be judged in isolation.
A level of debt that is normal in one industry may be unusually high in another.
What is cash-flow analysis?
Cash-flow analysis asks a straightforward question:
Where will the money come from to repay the bank?
For a salaried consumer, the answer may be monthly employment income.
For a company, repayment might depend on revenue from customers.
A credit analyst therefore studies whether cash generation is:
- Sufficient
- Reliable
- Sustainable
- Predictable
This is often more important than simply looking at how valuable the borrower’s assets are.
Banks generally prefer lending that can be repaid from normal cash flow rather than relying on selling assets after the borrower runs into trouble.
What is collateral?
Collateral is an asset that provides additional security for a loan.
Examples include:
- Property
- Vehicles
- Equipment
- Investments
- Cash deposits
- Certain business assets
If the borrower defaults, the bank may have rights over the security, subject to the credit agreement and law.
But collateral does not automatically make weak lending safe.
A good credit analyst still wants to understand whether the borrower can afford the repayments without the bank having to recover and sell assets.
What is a credit score?
In consumer lending, a credit score summarises aspects of a borrower’s credit profile into a numerical risk indicator.
Banks can use bureau scores together with their own internal information and lending models.
The score may influence the decision, but it is rarely the only factor.
A bank can also look at:
- Affordability
- Income
- Existing debt
- Account behaviour
- Product risk
- Internal customer history
Credit analysts working with larger businesses rely less on a simple consumer-style score and more on detailed financial analysis and internal risk ratings.
What is an internal credit rating?
Banks can assign their own risk rating to borrowers.
The rating represents the bank’s assessment of the probability that the customer may fail to meet its obligations.
For some large banks, these ratings also feed into regulatory capital calculations.
The Prudential Authority specifically regulates internal rating systems through its guidance for banks using internal ratings-based credit-risk approaches.
That makes credit analysis important not only for the individual lending decision but also for how banks measure risk across entire portfolios.
What is a credit recommendation?
After completing the analysis, the analyst usually produces a recommendation.
It could be:
- Approve the requested facility
- Approve a smaller amount
- Approve subject to conditions
- Request additional information
- Require more security
- Change the repayment structure
- Decline the application
The analyst may also recommend:
- An internal risk grade
- Lending limits
- Loan covenants
- Review frequency
- Conditions that must be met before funds are released
The final authority depends on the bank’s internal delegation structure.
A junior analyst generally does not personally approve a massive corporate loan.
What is a credit committee?
Large or higher-risk lending decisions are often reviewed by a credit committee or senior credit authority.
The analyst may prepare the credit paper and present the case.
Committee members can challenge assumptions such as:
- Revenue forecasts
- Debt levels
- Security values
- Economic outlook
- Industry risks
- Repayment ability
This means strong communication matters.
You may have done excellent financial analysis, but you still need to explain the risk clearly enough for someone else to make a decision.
What happens after the bank approves the loan?
Credit analysis does not necessarily end when the money is paid out.
Banks monitor borrowers throughout the life of a facility.
A credit analyst may review:
- Updated financial statements
- Repayment performance
- Changes in debt
- Covenant compliance
- Industry developments
- Management changes
- Security values
The bank wants to identify deterioration before a borrower reaches the point of default.
This monitoring function is particularly important in commercial and corporate banking.
What is a covenant?
A covenant is a condition included in a credit agreement.
A business borrower might be required to maintain a particular financial position, such as keeping debt below an agreed level relative to earnings.
Covenants can provide an early warning when financial performance begins weakening.
Credit analysts may calculate covenant ratios regularly and identify breaches.
A breach does not always mean the bank immediately demands full repayment. It can trigger further discussion, tighter monitoring or changes to the lending arrangement.
What happens when a borrower starts struggling?
The account may receive closer attention.
The analyst could:
- Review updated cash flows
- Reassess the risk rating
- Test different financial scenarios
- Recommend reduced limits
- Request additional security
- Consider restructuring options
South African banking regulation includes specific treatment for distressed restructured credit exposures. The Prudential Authority’s current Credit Risk Roadmap forms part of the framework banks use as credit exposures become more complex or distressed.
Is credit analysis the same as debt collection?
No. A credit analyst primarily assesses and monitors lending risk. Collections teams focus on recovering money after payments have been missed.
The functions can interact, particularly when a borrower becomes distressed, but they are different careers.
Credit is mostly about:
Should we take this risk, and under what conditions?
Collections is more about:
How do we recover money once repayment has become a problem?
Is a credit analyst the same as a financial analyst?
No, although the skills overlap. A financial analyst may analyse company performance, budgets, investments or business decisions.
A credit analyst focuses specifically on whether a borrower can meet financial obligations.
Both may use:
- Financial statements
- Excel
- Forecasting
- Ratios
- Financial models
But the final question is different. A financial analyst may ask whether a company is profitable or attractive as an investment.
A credit analyst asks whether it will repay its debt.
Is a credit analyst the same as an investment analyst?
No. An investment analyst is generally interested in the potential return from owning an investment.
A credit analyst is more focused on avoiding loss and receiving repayment.
Imagine a company whose shares could potentially rise 50%, but which also carries extremely high debt. An equity analyst may find the upside attractive.
A credit analyst may be much more concerned about whether the company can continue servicing its debt.
That difference in mindset is fundamental.
What qualifications do credit analysts need?
There is no single qualification required for every credit-analysis role.
Common degrees include:
- Finance
- Accounting
- Economics
- Business science
- Statistics
- Mathematics
- Actuarial science
The appropriate background also depends on the type of credit work. Traditional commercial credit may favour accounting and finance.
Credit-risk analytics can place much greater emphasis on mathematics, statistics and data science.
Standard Bank’s current banking risk analytics graduate programme targets graduates from fields including statistics, mathematics, econometrics, actuarial science, computer science and information systems for work involving credit decisioning, risk analytics and impairment models.
That illustrates how credit has become both a finance profession and a data profession.
Do you need to be a CA(SA)?
No.
CA(SA) can be valuable, particularly for corporate and commercial credit analysis, because it provides a strong understanding of financial reporting.
But many credit analysts come from other backgrounds.
A bank may value different qualifications depending on whether the position involves:
- Corporate financial analysis
- Retail scorecards
- Statistical modelling
- Property finance
- SME lending
- Portfolio risk
The job specification matters more than pursuing CA(SA) simply because you want to work in credit.
Is CFA useful for credit analysis?
It can be, particularly in institutional credit, debt markets, investment banking and corporate analysis.
The CFA curriculum includes areas such as:
- Financial statement analysis
- Fixed income
- Corporate issuers
- Economics
- Quantitative analysis
For a retail banking credit analyst, however, CFA may be much less important than practical credit, data and banking experience.
Choose additional qualifications based on the part of credit you want to enter.
Which Excel skills do credit analysts need?
Excel is still widely useful in credit analysis.
Important skills can include:
- Financial formulas
- Pivot tables
- Lookup functions
- Scenario analysis
- Data cleaning
- Financial models
- Ratio calculations
Commercial and corporate analysts may build forecast models to test whether a borrower can repay debt under different assumptions.
Being able to create a complicated spreadsheet is not enough.
The model must also make financial sense.
Should credit analysts learn SQL?
SQL is increasingly useful in roles involving large lending portfolios.
A retail bank may have millions of customers and transactions. Analysts cannot review those records manually.
SQL can help you:
- Extract customer data
- Analyse repayment behaviour
- Group accounts by risk
- Examine defaults
- Identify portfolio trends
For credit-risk analytics, SQL can be a very valuable skill.
Is Power BI useful in credit?
Yes. Power BI can be used to monitor:
- Arrears
- Defaults
- Portfolio growth
- Approval rates
- Risk segments
- Industry exposure
- Geographic exposure
- Collections performance
It is especially useful when management needs recurring portfolio reports.
A commercial credit analyst may not spend every day building dashboards, but understanding business intelligence can still broaden your options.
Do credit analysts use Python?
Some do. Python is most relevant in quantitative credit-risk roles.
It can be used for:
- Statistical modelling
- Data analysis
- Credit scoring
- Automation
- Machine learning
- Portfolio modelling
You do not need Python for every credit analyst job.
If your goal is traditional commercial or corporate credit, accounting, Excel and financial modelling may be more immediately valuable.
If you want to move into risk analytics or model development, Python becomes much more useful.
How is AI changing credit analysis?
AI and machine learning can process larger amounts of borrower and transaction data than a person can review manually.
Banks can use models to support:
- Application screening
- Fraud detection
- Risk scoring
- Early-warning systems
- Portfolio monitoring
But this does not eliminate the need for professional judgement.
High-impact credit decisions still raise questions about model accuracy, fairness, explainability and regulatory oversight.
For complex corporate lending, an algorithm also cannot replace understanding management quality, industry dynamics and the commercial logic behind a transaction.
What skills make a strong credit analyst?
Strong credit analysts combine numbers with judgement.
Important skills include:
- Financial statement analysis
- Accounting
- Cash-flow analysis
- Credit-risk assessment
- Excel
- Financial modelling
- Attention to detail
- Commercial awareness
- Written communication
- Critical thinking
For data-heavy roles, add:
- SQL
- Power BI
- Statistics
- Python
Communication is particularly important because credit analysts often need to explain why a lending proposal is acceptable or too risky.
Do you need strong accounting skills?
For business, commercial and corporate credit, accounting is extremely useful.
You need to understand what financial statements are telling you and when the accounting figures may hide a cash-flow problem.
For example, you should be comfortable asking:
- Why did receivables rise faster than sales?
- Why is inventory increasing?
- Why is profit growing while cash flow is weakening?
- How much debt is due within the next year?
- Can the business service interest if earnings fall?
Those questions are at the heart of commercial credit analysis.
Is credit analysis mainly about maths?
Not necessarily.
Most credit roles require comfort with numbers, but traditional commercial analysis is not advanced mathematics.
You need to calculate ratios and understand financial relationships.
More quantitative roles, such as credit modelling, can require considerably stronger mathematics and statistics.
The field therefore offers options for both finance-oriented and quantitatively oriented graduates.
Where do credit analysts work?
Banks are major employers, but credit analysis also exists outside traditional banking.
Employers can include:
- Commercial banks
- Development finance institutions
- Asset managers
- Corporate lenders
- Vehicle-finance companies
- Fintech lenders
- Credit insurers
- Investment firms
- Large companies with internal credit teams
The underlying skill of assessing whether someone is likely to repay money is useful across many financial-services businesses.
How much does a credit analyst earn in South Africa?
Current salary data varies considerably by experience, location and type of credit work.
Indeed currently estimates an average base salary of about R370,344 per year nationally, based on its reported South African Credit Analyst data updated in June 2026. Its current South African Credit Analyst salary data also shows a broad reported range because junior, senior and specialist positions can differ substantially.
Johannesburg can pay more. Indeed’s Johannesburg Credit Analyst salary data currently estimates average base pay at about R512,878 per year, although the sample is relatively small and should be treated as an indication rather than a guaranteed market rate.
Pay can rise significantly for senior analysts, specialised corporate credit professionals and managers.
What affects a credit analyst’s salary?
Major factors include:
- Experience
- Bank or employer
- Type of credit
- Size of lending exposures
- Qualifications
- Data skills
- Location
- Seniority
A junior analyst assessing straightforward SME lending may earn considerably less than a senior corporate credit analyst reviewing complex multi-million-rand facilities.
Credit modelling and specialist risk skills can also lead to different compensation from traditional credit-underwriting roles.
What can you progress into after credit analysis?
Credit provides several career directions.
Possible next steps include:
- Senior Credit Analyst
- Credit Manager
- Credit Risk Manager
- Corporate Banker
- Relationship Manager
- Portfolio Manager
- Risk Analyst
- Credit Modelling Specialist
- Head of Credit
- Chief Risk Officer
You can also move into related areas such as corporate finance, commercial banking or investment analysis depending on your experience.
A strong credit background teaches you to examine businesses with a particularly disciplined view of risk.
Is credit analysis a good career for finance graduates?
It can be an excellent choice if you enjoy analysing businesses and financial information but do not want a career focused purely on accounting.
You get exposure to:
- Banking
- Financial statements
- Lending
- Business models
- Risk
- Industries
- Data
It can also provide a strong commercial education because you spend your time asking how businesses make money and what could cause them to fail.
The field is evolving too. Standard Bank’s focus on graduates with statistics, actuarial science, mathematics and data backgrounds for credit decisioning and risk analytics work shows that modern credit teams increasingly combine finance with data and technology.
Who is credit analysis best suited to?
You may enjoy the field if you naturally ask questions such as:
- Can this person afford the loan?
- Where will the repayment money come from?
- What could go wrong?
- Are these forecasts realistic?
- Is the borrower already carrying too much debt?
- What happens if sales fall?
- Is the proposed security actually valuable?
Credit analysts are paid to be curious and sceptical without automatically being negative.
The goal is not to reject lending.
It is to help the bank make good lending decisions at an acceptable level of risk.
That makes credit analysis one of the clearest careers for someone who wants to combine accounting, financial analysis, banking, risk and increasingly data technology.
